digital marketingseo aeo geo
How AI and Social Media Are Reshaping Digital Brand Discovery
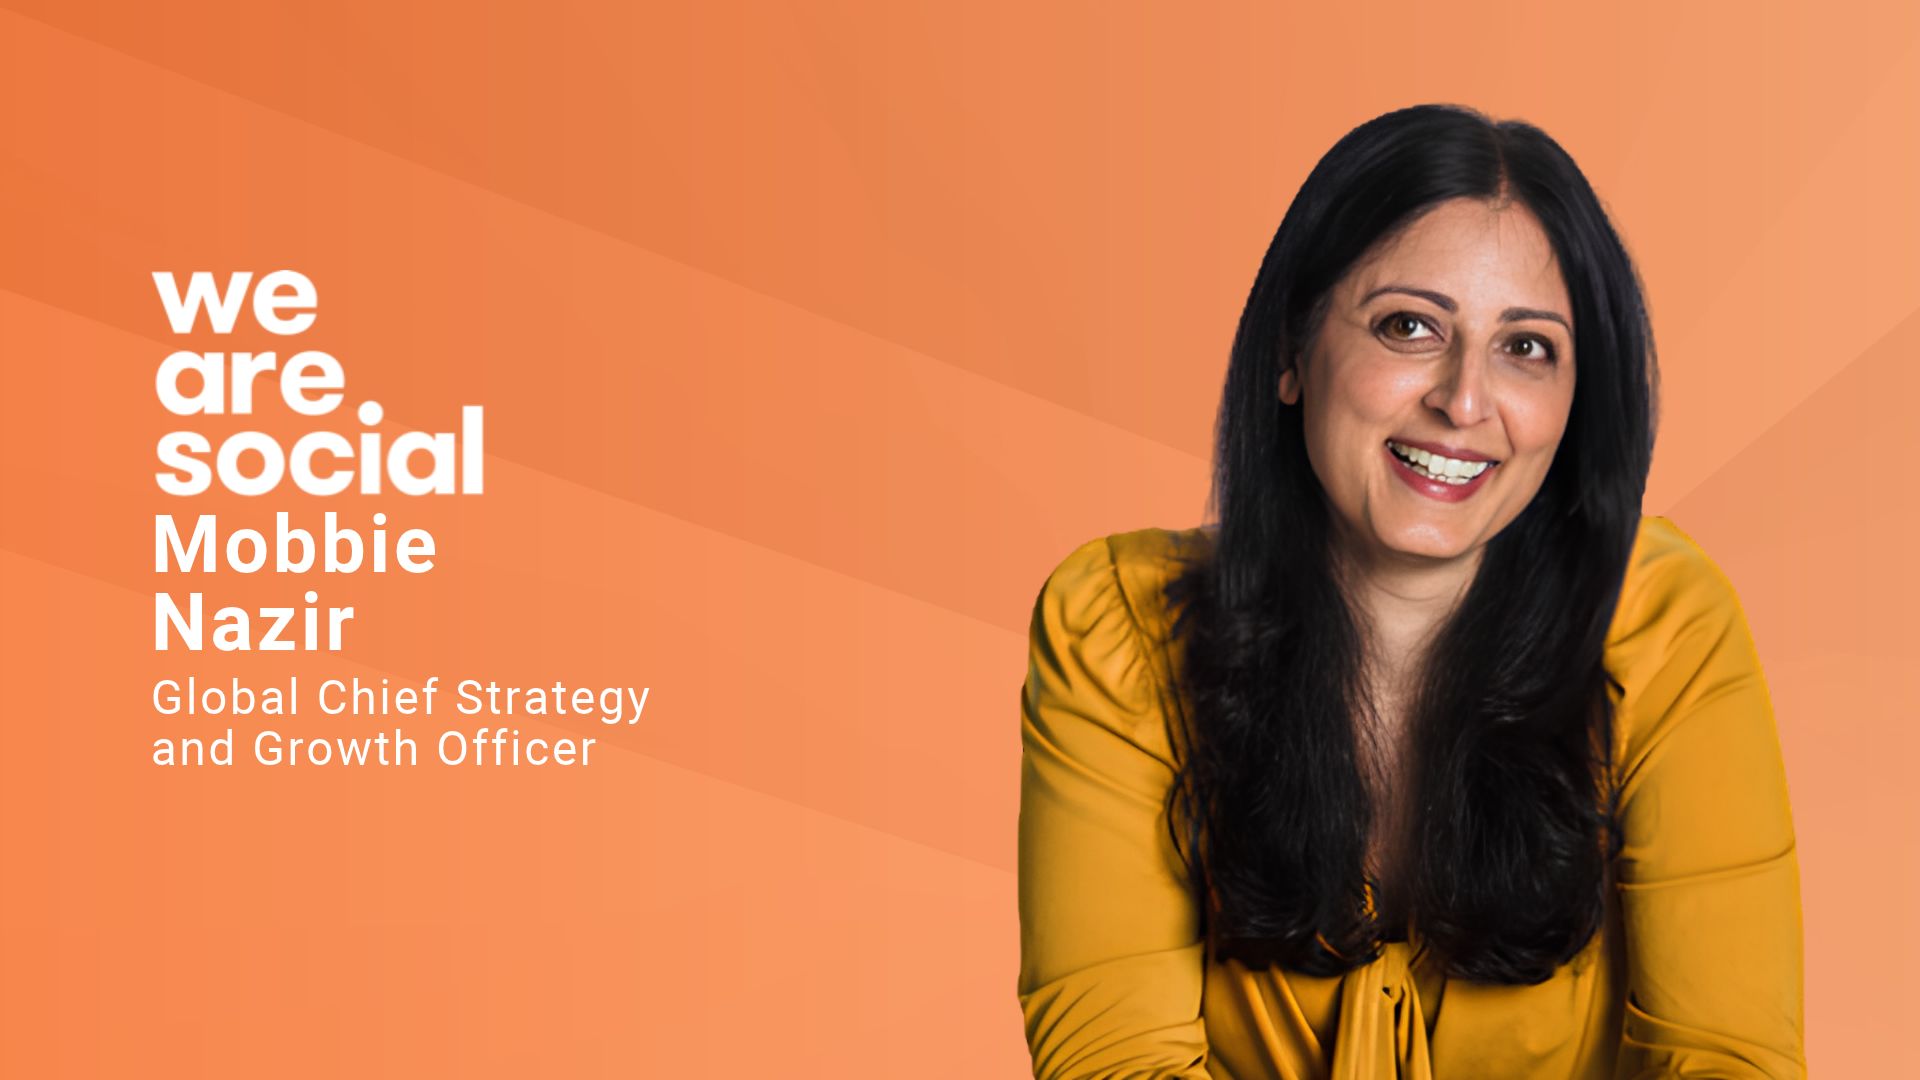
1. The Digital 2027 report points to rapid growth in Generative AI adoption alongside continued expansion in social media use. What do these developments reveal about how consumers are changing the way they discover information, evaluate brands, and make purchasing decisions?
What we’re seeing across the data is a convergence of social and AI. With GenAI users reaching 3.2 billion (+57% year-on-year) right as social hits nearly 70% of the planet, consumers aren’t swapping one habit for another.
The purchase funnel is now a loop. Over 60% of people using GenAI are turning to it to find information, and another 40% are treating it as a soundboard for advice. People are done wading through endless search engine results. They want AI to act as a personal curator, doing the heavy lifting on specs, comparisons, and filtering out friction.
At the same time, cultural validation still lives on social. While traditional search is still strong, social’s impact is important for younger demographics in particular: 46.9 percent of internet users aged 16 to 24 use social platforms as their primary source of information when researching brands and potential purchases - higher than any other channel.
For brands, this means your strategy can't rely on a single media platform any more. Consumers are using AI for the rational breakdown, but they still look to communities, creators, and peers on social to see if a brand actually resonates with them. While AI is an advisor, human agency still signs off on the decision.
2. The report highlights declining traffic across web domains alongside the growth of AI platforms and native apps. Are we seeing a fundamental shift away from the traditional web, or is consumer attention simply moving to different digital environments?
I wouldn't frame this as people abandoning the internet. It’s a migration of attention toward more immersive, native environments.
The numbers tell a very specific story: traffic across the top 10,000 domains dropped nearly 7% over two years, shaving off 6.6 billion hours a month. But desktop traffic only slipped less than 1%. The real drop came from the mobile web, falling 11%. People haven't stopped browsing on their phones; they’ve bypassed the browser in favour of native social feeds, direct messaging, and dedicated apps.
Native apps and social platforms are where inspiration, culture, and discovery happen. The website is now the destination where people arrive once they're already ready to buy.
3. Generative AI adoption is growing rapidly, but consumers still use search engines than AI platforms when researching brands. How should marketers interpret this gap between AI adoption and AI brand discovery?
Even with over 3.2 billion people using GenAI monthly, search engines are still 74% more likely to be used for brand research - for now, at least. Search is also backed by $376 billion ad spend and decades of muscle memory.
The real headline is how fast search is changing. Pre-purchase brand research on traditional search dropped from 51% to 45% in just two years.
Yes, paid search spend is still doing the heavy lifting for near-term conversions today. But if brands are only optimising for links, they are already behind. Brands have to start balancing traditional SEO with GEO. When a consumer asks an LLM for a recommendation, your brand has to be part of the conversation.
4. The report indicates that social media and online video now account for a substantial share of consumers' digital attention. How should brands rethink the role of social platforms within their broader marketing strategies?
When you see that people are spending over 19 hours a week on social and online video, it’s definitive proof that social isn’t an add-on. Social is the plan.
What’s fascinating from a strategic point of view is the sheer volume of cross-platform mobility. The average user is active across up to seven different platforms a month, creating a massive audience overlap of upwards of 75% between YouTube, Instagram, Facebook, and WhatsApp.
For brands, this means the legacy mindset of "we have to be everywhere all at once" isn't accurate. You don't need to chase reach everywhere; you’re talking to the same people in different mindsets. Instead, focus on two or three core platforms, picking them based on distinct creative and formats.
5. How should businesses rethink the relationship between brand building and performance marketing when consumers discover a brand on one platform but convert somewhere else or never visit the brand's website at all?
The website isn’t always the end goal. Only 24% of people discover brands on brand websites, and visits to the world’s top websites have fallen almost 7% in two years.
Attention has shifted to social, with seven in ten people now researching brands on social before they buy. And social has essentially collapsed the journey from discovery to purchase. Not only does the fyp make it easier to serendipitously find products you'd fancy via the algorithm, big social has also been investing in social commerce capabilities that enable purchases to happen seamlessly within the app or via creators.
And if the decision happens in the feed, the people in that feed matter most.
Social users are more likely to follow creators than the brands they actually buy from, so creators are often the ones doing the persuading. Take for example, how KFC turned gym-goers’ viral protein hacks into menu items to drive sales. Creators don’t just help a brand earn relevance in the feed. They move people towards purchase.
So the line between brand building and performance has essentially disappeared. The content that makes people want something is the same content that sells it, wherever the checkout happens. Businesses should measure it that way: by every sale it influences, not just the clicks they can track.
7. As digital behavior shifts, how should marketing leaders reassess budget allocation across social media, online video, paid search, organic search, and emerging AI discovery channels?
Reassessing your media allocation starts with understanding the contribution your media channels have against your goal and maximising your owned & earned. There is no one size fits all approach. Search still captures $300+ billion a year and there are entire businesses built on the back of TikTok. What these brands do better than anyone else is understanding who their customers are, where they are and how to create and amplify content in the right medium.
Equally, it is impossible to do everything well. Mapping out your core platforms for your audience and optimising them to maximise business impact is better than a fragmented approach and often serves larger impact. Identifying where customers are and where you can have a higher SOV could influence your audience more than you realise. We all talk TikTok strategy, but when was the last time you explored Snap? 90% of users in the US are younger than 35.
8. Looking ahead, what do you believe will distinguish brands that adapt successfully from those that continue to rely on outdated assumptions about digital discovery and engagement?
Winning brands accept that their website is no longer the default front door. Instead they deliver complete brand experiences balanced across paid, owned and earned media. That means natively within social feeds, video platforms, and AI responses. It means a solid PR approach, and a robust and effective creator strategy. If someone can discover and evaluate you without ever visiting your .com, that’s a win.
Ultimately, the leaders will play a dual game: optimising to be recommended inside AI engines, while making their owned spaces high-value destinations for retention rather than casual discovery.